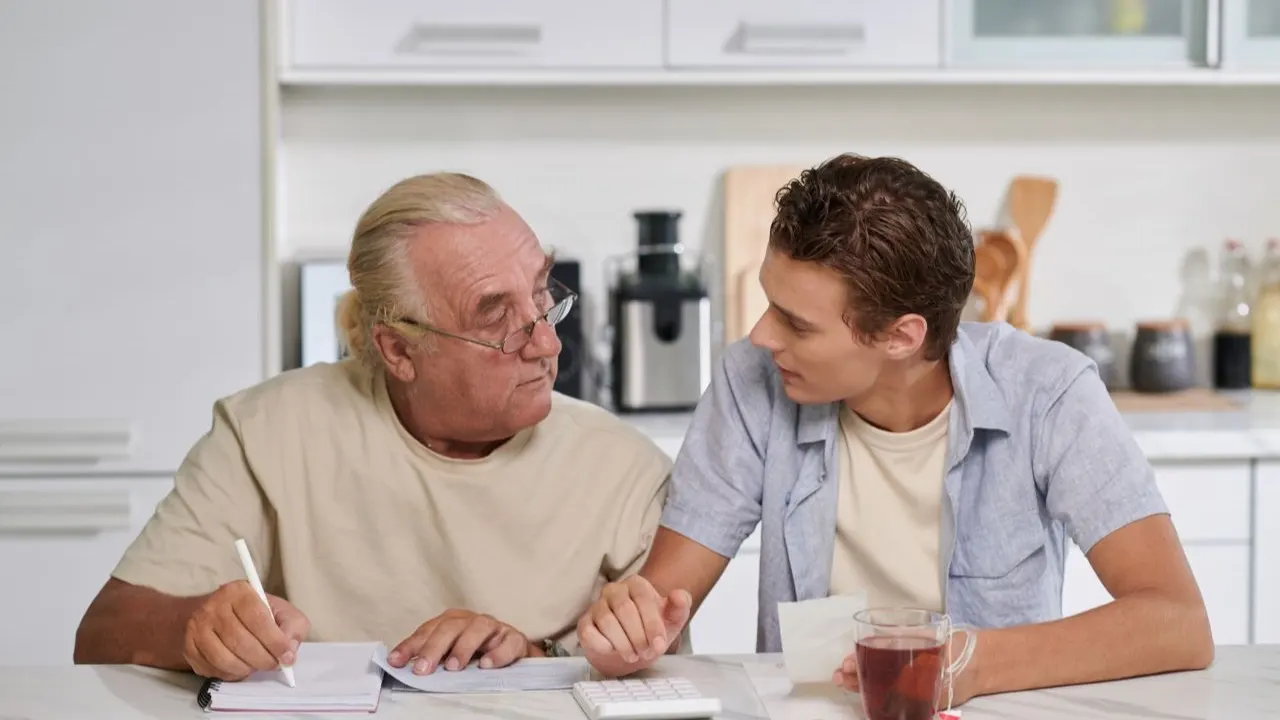
At Achieve, we're committed to providing you with the most accurate, relevant and helpful financial information. While some of our content may include references to products or services we offer, our editorial integrity ensures that our experts’ opinions aren’t influenced by compensation.
Personal Loans
Co-signing a personal loan: 6 steps to success
Updated Oct 17, 2026
Written by
Reviewed by
Key takeaways:
When you co-sign a personal loan, you're legally responsible for repaying the debt if the borrower defaults.
Read any legal contracts and know exactly what happens if the borrower fails to repay the co-signed personal loan.
Make sure co-signing won't derail your own financial plans.
You love your friends and family, and you want them to succeed. That's why many people don't hesitate when asked to co-sign a personal loan. It can be a beautiful gesture and a real way to give your loved ones a leg up.
However, it's also important to protect yourself. Co-signing a loan impacts your own credit and financial situation, and you need to safeguard those things.
Co-signer vs co-borrower
One key thing to understand is exactly what you're agreeing to. Co-signing is different from being a co-borrower. A co-borrower or joint borrower shares both access to the loan funds and responsibility for paying it back.
A co-signer promises to repay a loan if the borrower can't, but you don't have any legal right to the loan proceeds. So you could be on the hook for money you never touch.
As nice a gesture as co-signing a loan can be, it could also be the cause of a broken relationship (and ruined credit) if things go wrong. Consider these steps to help protect yourself before you agree to co-sign anything.
1. Check your own credit and finances
Someone who can't qualify for a loan often has a limited credit history, low credit score, or insufficient income to qualify without assistance. If asked to co-sign a personal loan, it's important to first make sure you actually qualify to help.
Review your own credit reports and check your credit score. Go through your monthly budget very closely, too. Would you be able to pay back the loan if the borrower defaults? If not, it's probably better to help the borrower find other options rather than co-signing a personal loan.
2. Consider your future borrowing needs
Even if the borrower makes every payment on time, a co-signed personal loan can still impact your ability to borrow money in the future. That's because future lenders may include co-signed loans when they calculate how much of your money is available to make a new loan payment.
Lenders use your debt-to-income ratio (DTI) to calculate the affordability of a new loan payment, and having a co-signed loan on your credit report means that you may not qualify to borrow as much.
If you don't plan to borrow money during the loan term, it may not be a problem—but if you expect to buy a home soon, reconsider co-signing. Mortgage lenders typically require you to prove that the borrower has made at least 12 on-time payments before leaving the co-signed loan out of your DTI.
3. Review the borrower's finances and plans
You've done the hard work to make sure you can afford to repay the loan if necessary. Next, do the same for the borrower. Ask why they need the loan, and how they plan to pay it back.
It's a bad sign if they're borrowing to cover basics because they overspend, or to make a purchase they don't need. It's better if they're making a necessary buy and have already worked out how they'll repay the loan.
The person you're co-signing for should be comfortable sharing their finances with you. Ask to see their budget. If they don't have one, have them make a budget. Create a contingency plan as well. If their hours are reduced at work, for instance, how will they make up the shortfall?
4. Clarify the fine print in the loan agreement
Have you ever rushed through the legalese when signing a contract? It's tempting, but this is one time to slow down and see what it says about co-signers. After all, it's a legal contract.
In particular, make sure you know the answers to these questions:
How soon will you be notified of a late payment? Before it gets reported as a 30-day late payment to credit bureaus?
What is your responsibility if you have to repay the loan? Principal balance only? Or late charges, interest, court costs, and collection fees?
Will the lender allow you to continue payments as usual, or will they demand the loan be repaid all at once, and in full? (This is called acceleration.)
Does the lender offer a co-signer release at any time during the loan? Under what conditions?
A final point here: It's a good idea to keep any copies of the loan agreement for your own files in case you need to refer to them later. You may also wish to make an official, written agreement with the borrower covering your access to account information and what happens if you have to make one or more payments.
5. Get payment notifications
Even with the best intentions, life happens. The borrower might lose a job, get into an accident, or be hospitalized and unable to make payments or even communicate. Whatever the reason for non-payment, you may not find out in time to prevent damage to your credit score.
That's why it's crucial to set up a system so that you know the payment is made on time—and if not, you have a chance to step in and avoid credit damage. Some lenders allow co-signers to have online account access or immediate missed payment notification. If not, ask the borrower to share their account access as a condition of co-signing for the loan.
6. Research state-specific co-signer protections
Some states offer safeguards to help co-signers. Now's a good time to check whether your state has any specific laws in place for this. You can do this by looking up your state's attorney general or banking agency.
If you've co-signed a personal loan in Michigan, for example, and the borrower misses loan payments, the lender is required to send you a letter and give you 30 days to respond before it can take any action against you.
Ready to shop for a loan with your loved one? They can check their rates through Achieve Personal Loans with no credit impact.
Author Information
Written by
Lindsay is a writer for Achieve. She's passionate about helping people learn how to manage their money better so that they can live the life they want. She enjoys outdoor adventures, reading, and learning new languages and hobbies.
Reviewed by
Gina Freeman has been covering personal finance topics for over 20 years. She loves helping consumers understand tough topics and make confident decisions. Her professional history includes mortgage lending, credit scoring, taxes, and bankruptcy. Gina has a BS in financial management from the University of Nevada.
Frequently asked questions about co-signing a personal loan
No, you can't take out a personal loan in someone else's name, because whoever signs the loan is legally responsible for repaying it. You may have two real ways to help:
As a co-signer, you guarantee repayment if the borrower can't pay. You're not a borrower and you're not entitled to any of the money.
Never sign a loan in another person's name or let someone borrow using yours, since that could be considered fraud.
Rarely. A co-signer can sometimes be removed from a personal loan, but this is not common. Lenders aren't likely to release you because it would increase their risk and deliver no benefit.
Lenders may be willing to release a co-signer after the borrower makes a predetermined number of on-time payments and is able to qualify for the loan without help. Otherwise, the co-signer remains obligated until the borrower pays off the loan or refinances it into their own name.
Ask the lender which options it offers before you sign, and make sure that matches what's in writing before you sign anything.
The difference between a co-signer and a guarantor comes down to when you're responsible for the debt. A co-signer is responsible from the very first missed payment, so the lender can ask you to pay as soon as the borrower falls behind. A guarantor pays only after the lender has exhausted its efforts to collect from the main borrower.
Both roles promise repayment. A guarantor just sits one step further back in the process. Read your agreement closely so you know which role you're taking on.
Related Articles

Adding a co-signer to a personal loan application could improve your approval odds and rate. Learn what lenders look for and how to apply with Achieve.


Learn how unsecured personal loans work, compare rates and terms to credit cards, and find out how to qualify — even with fair credit. Apply today.

Learn how to pay off credit card debt with a personal loan. Compare rates, lower your monthly payments, and get a plan to become debt-free faster.

Adding a co-signer to a personal loan application could improve your approval odds and rate. Learn what lenders look for and how to apply with Achieve.
Learn how unsecured personal loans work, compare rates and terms to credit cards, and find out how to qualify — even with fair credit. Apply today.
Learn how to pay off credit card debt with a personal loan. Compare rates, lower your monthly payments, and get a plan to become debt-free faster.